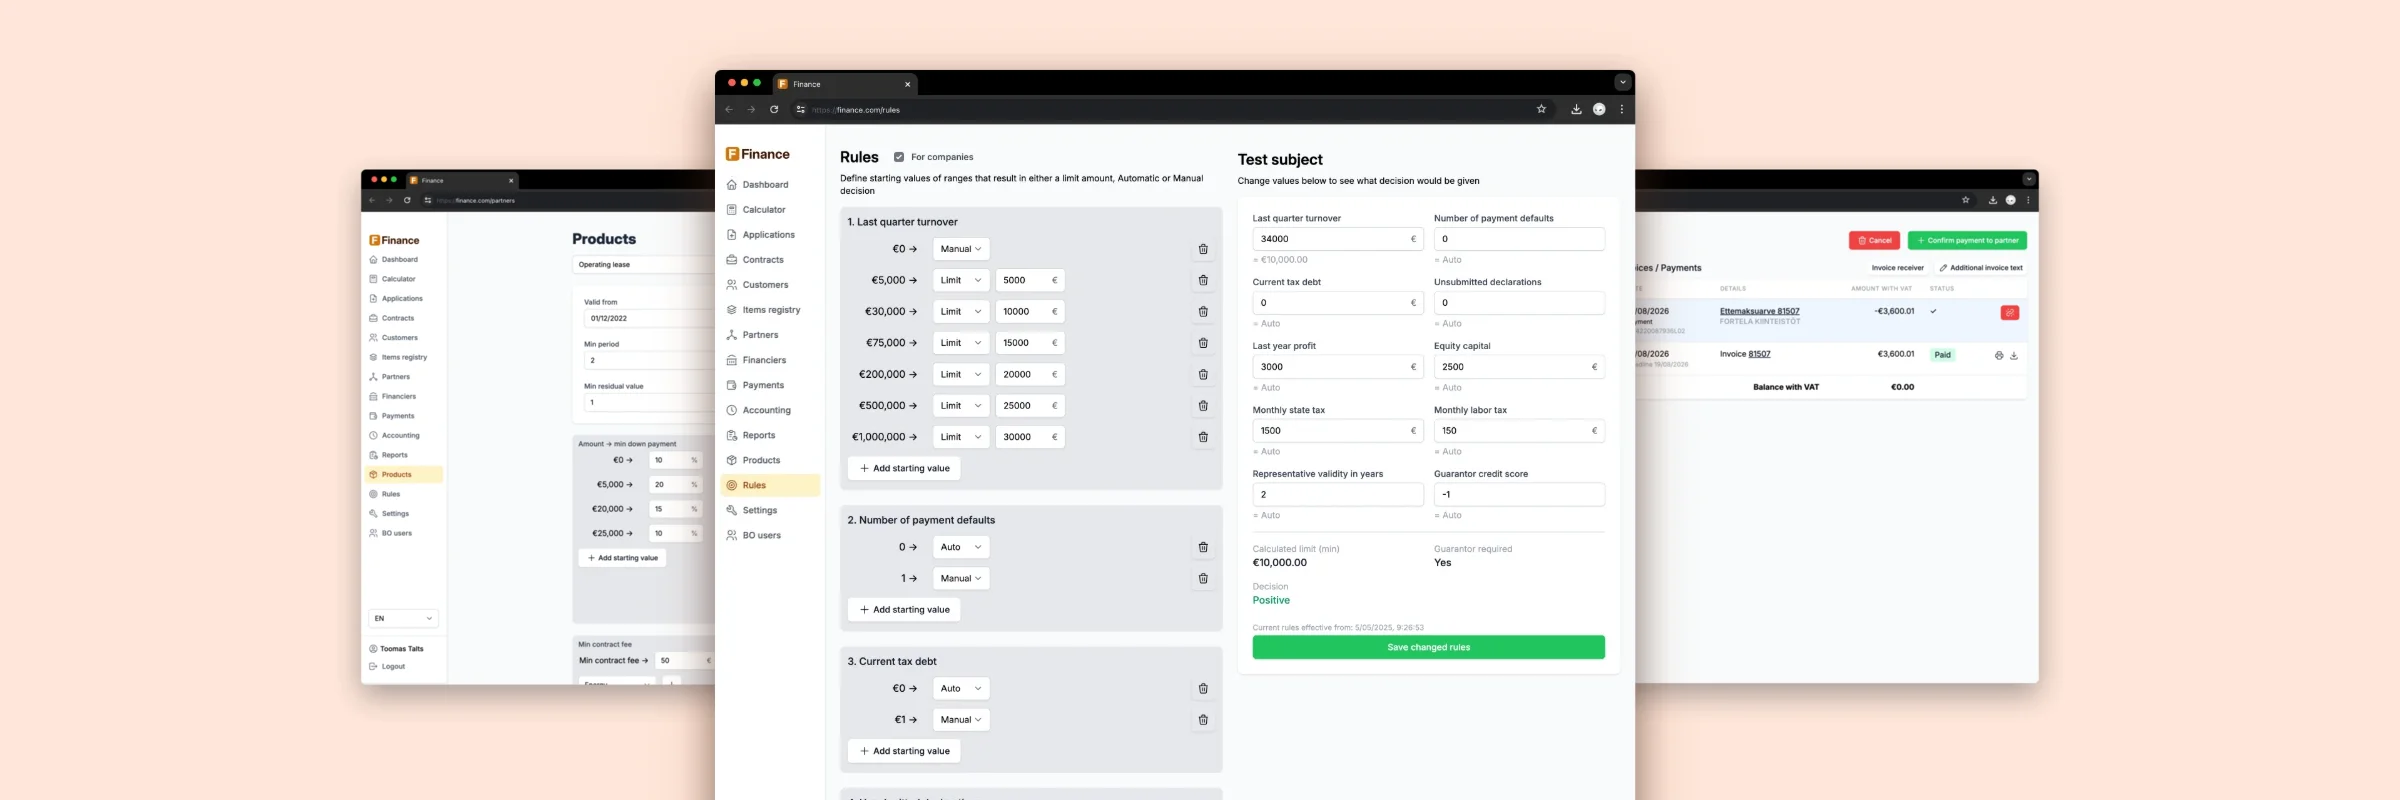
B2B purchase financing with automated credit decisions
End-to-end B2B equipment-finance platform, from partner application intake to customer contracting. An automated solution for financing purchases for corporate customers, where a significant number of cases are auto-decided. Built and delivered by Codeborne.
When it comes to automated credit decisions, plenty of success stories and widespread best practices are available for private customers. Not so many for companies. Too many variables to automate? Maybe so. For financing companies, there are usually many people behind every single credit decision. With their respective cost.
It does not have to be that way. We have built one solution for a common business case.
Our customer - a hardware merchant - sells various gardening tools and machines, including lawn mowers and tractors. The usual ticket falls under 50,000 euros. Many customers are companies, both small and large.
Purchases of that size can still significantly impact cash flow if paid out at once. How about adding a seamless financing flow here? That was the idea when we met.
The practice showed that when the retailer sends the company needing some financing, in relatively small amounts, to larger banks, the result may not be a purchase. The banks may not always want to deal with such smaller cases. These cases are too costly for their current processes. NB! This is not classical SME financing, but a lot smaller amounts.
Our customer had a strong vision to fill the gap, and so we continued together.
Today, dozens of merchants and a large number of business customers from all possible industries use the solution, and it has proven the business case for the customer. The system has been up and running for several years, and the loan loss rate has been significantly low.
Who can benefit from having such a system?
Larger retailers that sell items, the purchase of which can be financed with hire purchase. Even better if the company selling the goods has its own funds to finance the crediting, thus creating an additional revenue stream for its excess cash.
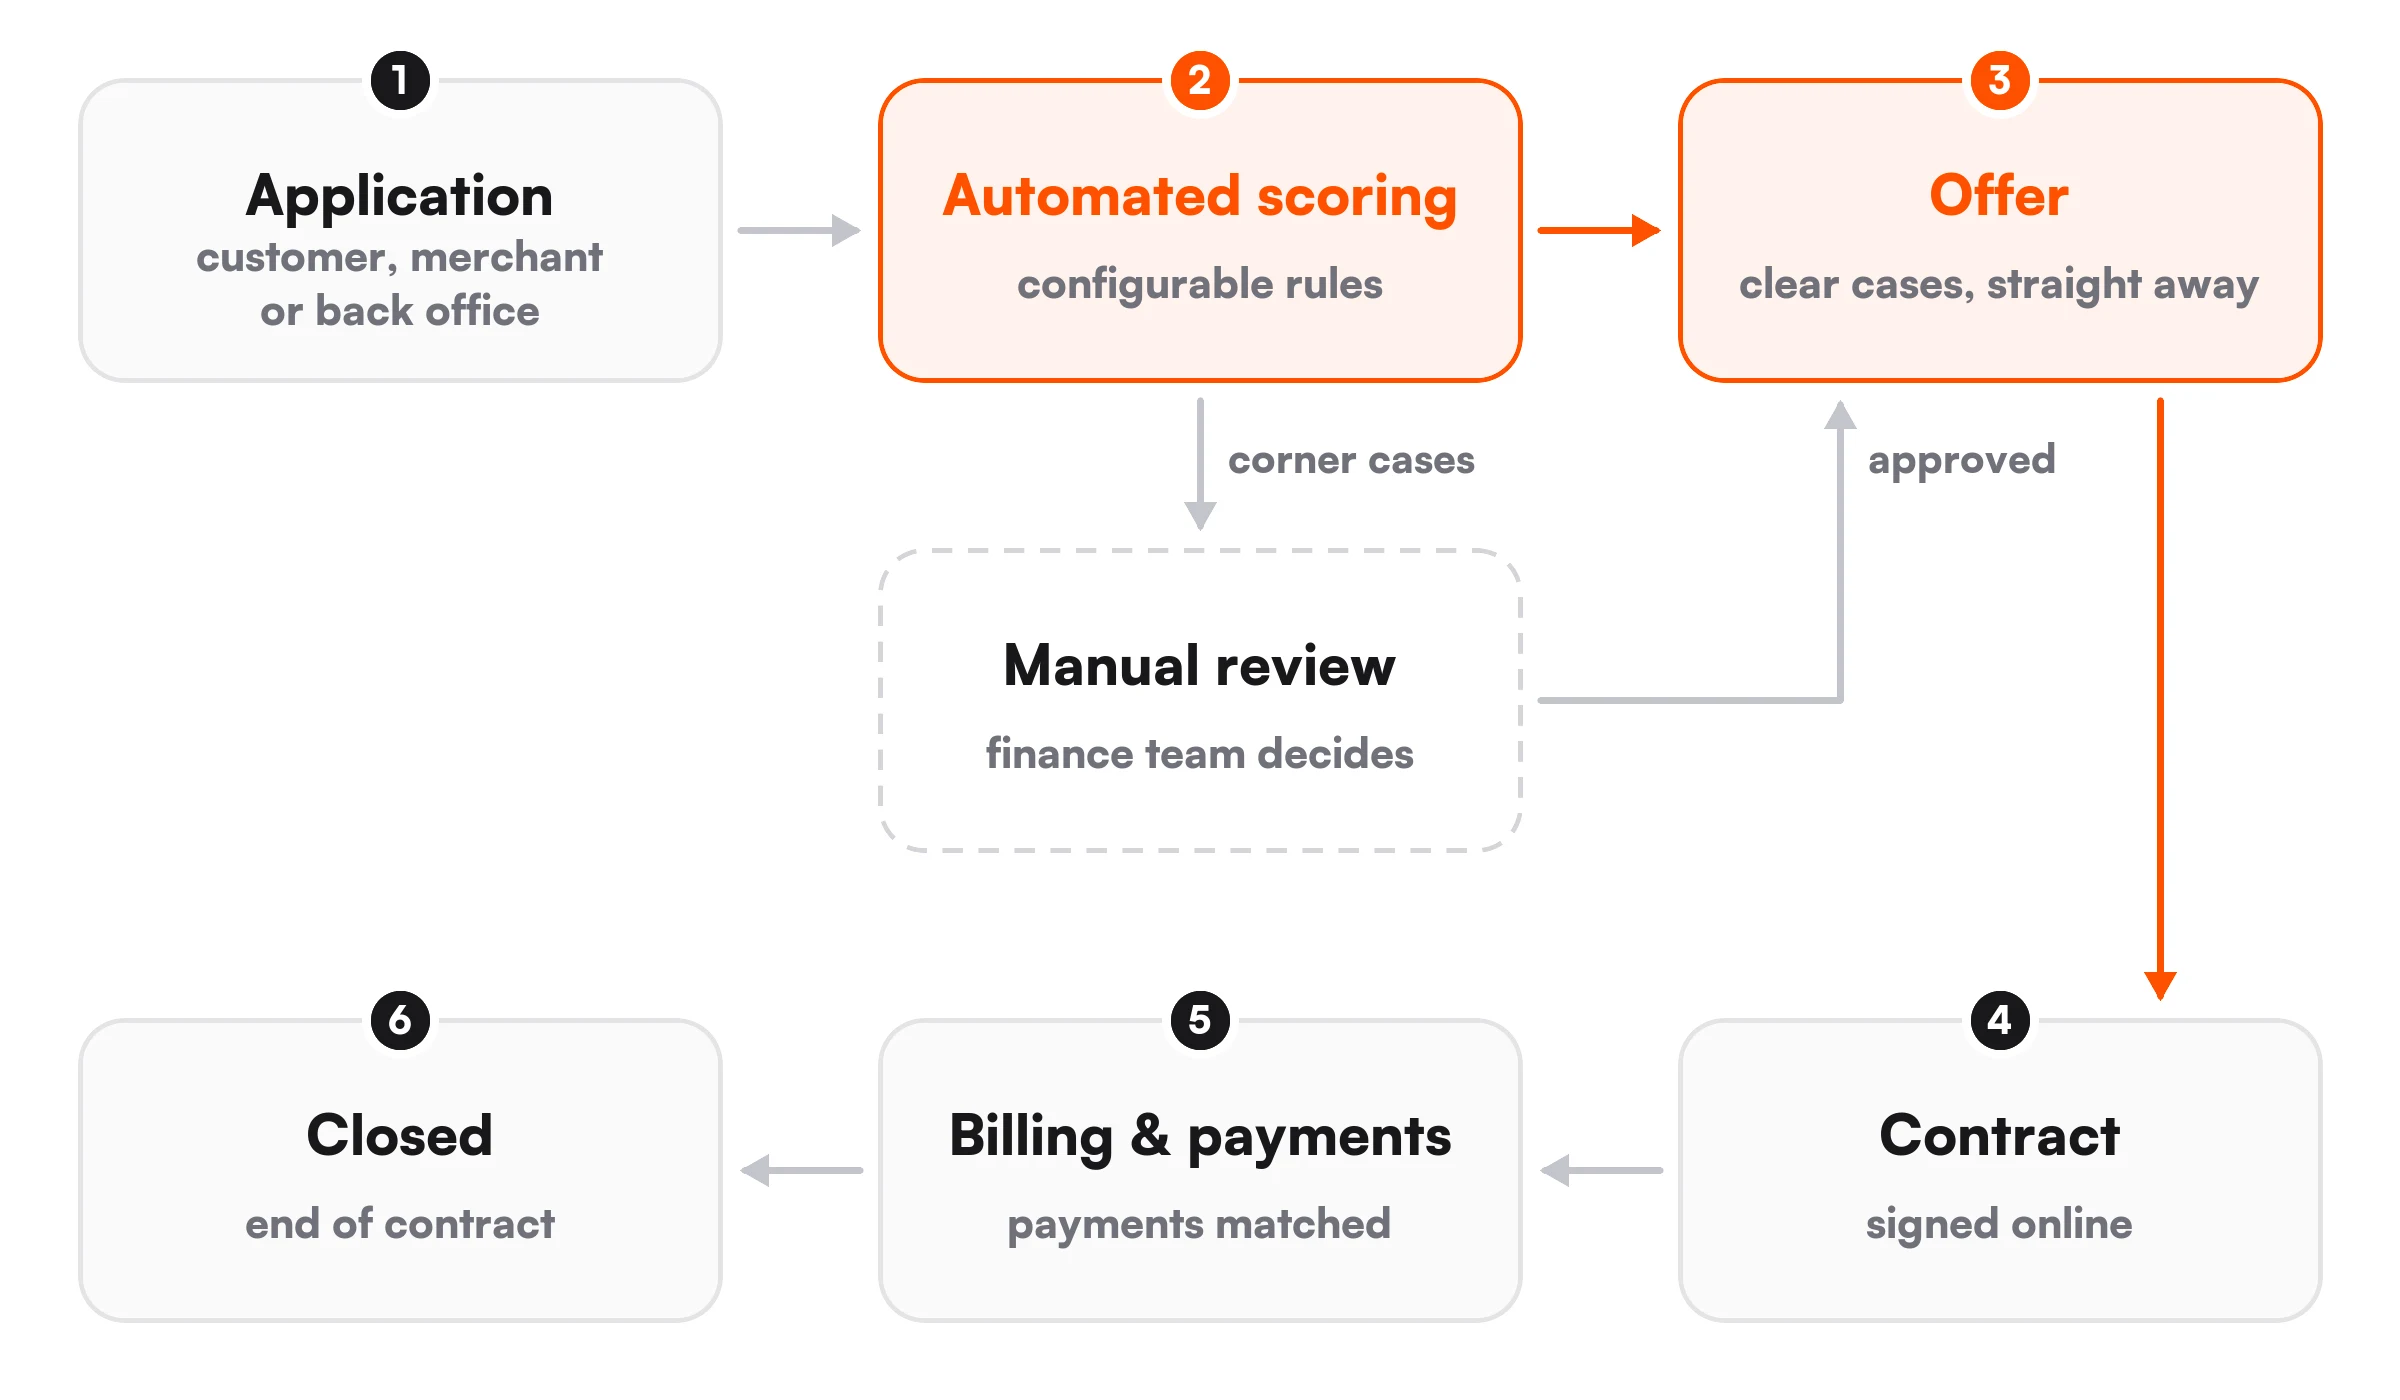
The entire credit lifecycle is covered
| Module | What it does |
|---|---|
| Applications | Can be started by the end customer, a partner or merchant, or a back-office expert at the financial institution. |
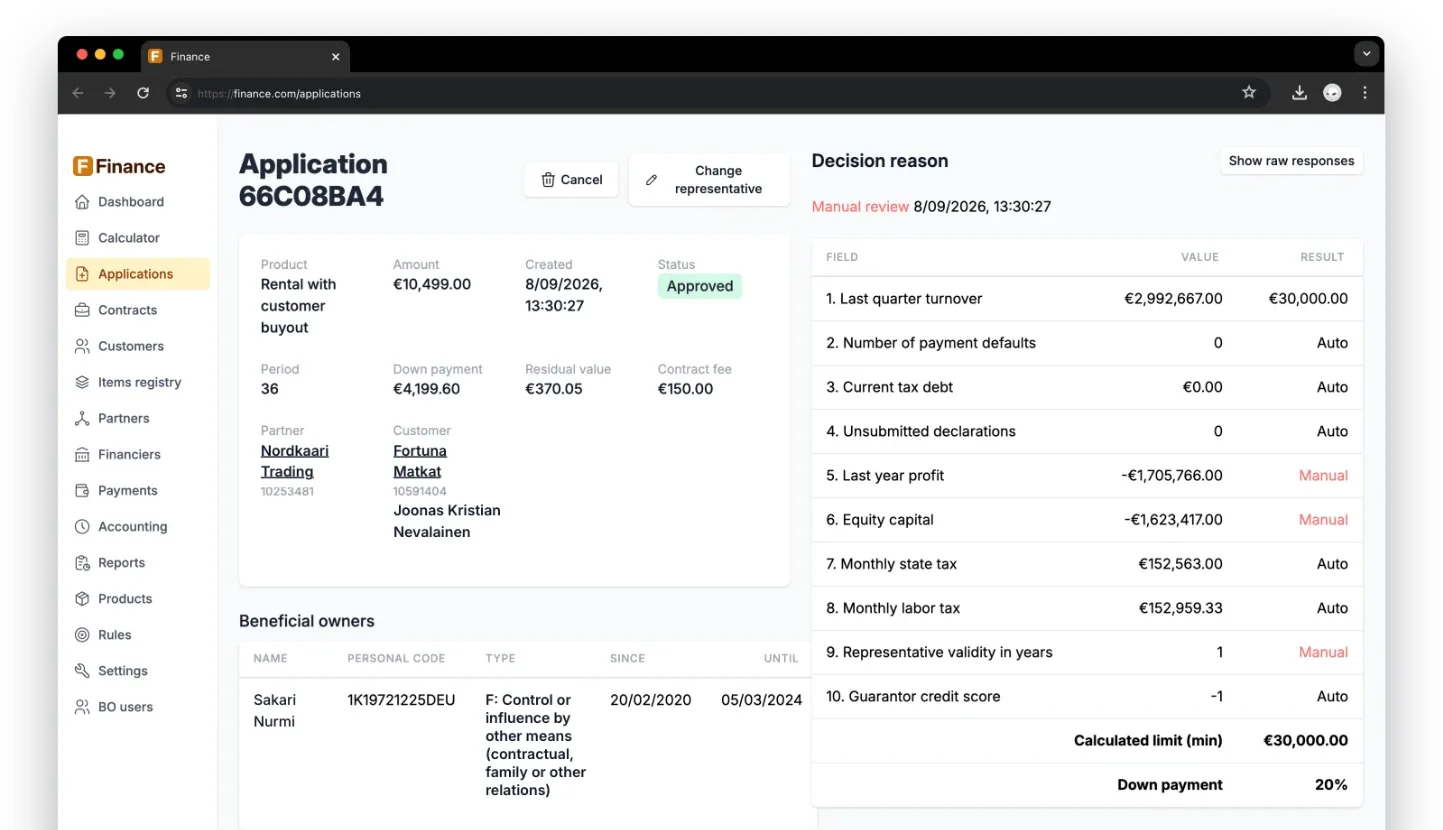
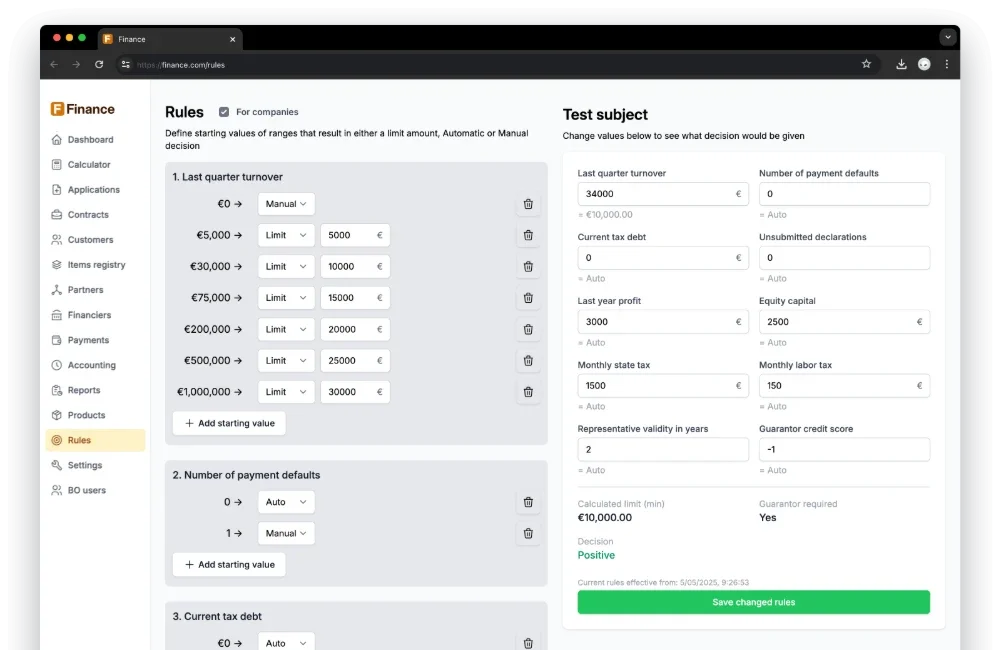
| Automated decision engine | Applications are scored against a configurable rule set the moment they arrive. Identity, credit data, exposure, and policy checks run automatically, and clear cases get an offer without anyone touching them. Corner cases fall into a manual flow. |
| The entire contract life-cycle: signing, amending, and termination | Contracts are generated straight from the approved offer, signed online, and tracked through every state from draft to closure. No paper at any step. |
| Product configuration | Product terms are configuration, not code: payment schedules, residual values, and how cost falls across the term are defined per product, so new offerings don't need new development. |
| Role-based portals | Each audience gets its own surface over the same core: merchants prepare and submit, the finance team assesses and decides, customers review and sign. Nobody sees screens meant for someone else's job. |
| Integrated ancillary services | Everything around the equipment (insurance, maintenance, delivery, setup) is priced into the same agreement, so the customer signs once and pays one schedule. |
| Integrated with external identity | Seven categories of external services are wired in, so identity checks, signatures, credit data, bookkeeping, CRM records, notifications, and payments all happen without leaving the flow. |
| Compliance ready | A compliant, auditable system, suited to regulated financial services, with clear controls and operational transparency. Every material action (submission, decision, amendment, signature) is recorded with who did it and when, so auditability is a property of the system, not an afterthought. |
| Scalability | Scalable bespoke software that combines a polished customer journey with robust back-office operations and configurable business rules. One platform serves both ends: a customer journey polished enough to sell through, and back-office operations robust enough to run the book, with configurable rules sitting between them. |
| White-label ready | Partners can offer embedded finance under their own brand. Partners front the experience under their own brand; origination, decisioning, and contracting run on one shared platform underneath. |
| Debtor management | |
| Billing management with matching incoming payments | |
| Collateral management | |
Looking to automate credit decisions for your business customers? Let’s talk.
Our recent stories
B2B purchase financing with automated credit decisions
End-to-end B2B equipment-finance platform, from partner application intake to customer contracting. An automated solution for financing purchases for corporate customers, where a significant number of cases are auto-decided. Built and delivered by Codeborne.
Building for the future of insurance: our work on Swedbank P&C insurance claims
Our founders wrote the core of this internet bank in 2006-2007. Twenty years later, we're back inside it.
Flowers for a new generation - live in one month with AI as the pair programmer
How a long-time client's idea for reaching younger customers became our first project built systematically with AI from end to end - prototype, code, and content - while keeping every line reviewed and owned by us.